Florida Homestead Exemption Rules For Out-of-State Buyers

Overview

  • Florida has no state income tax, but property taxes fund local services, and in the Vero Beach area you should budget roughly 1% to 1.5% of your purchase price per year, depending on location and which exemptions you qualify for.
  • The homestead exemption (now about $51,000 off assessed value) and the Save Our Homes assessment cap only apply to your permanent primary residence, so a snowbird second home does not qualify for either.
  • The biggest trap for out-of-state buyers is assuming the seller’s low tax bill is what you’ll pay, because Florida reassesses the property to full market value the year after you buy.
  • A second home still gets some protection through the 10% non-homestead assessment cap, just not the homestead exemption or the 3% Save Our Homes cap.
  • If you make Florida your primary residence, you file for homestead by March 1, and if you’re selling another Florida home you may be able to transfer up to $500,000 of built-up Save Our Homes savings to the new one.

If you’re moving to Vero Beach from up north, the property tax conversation usually starts with relief and ends with confusion. The relief is real: Florida has no state income tax, which is a big part of why you’re looking here in the first place. The confusion shows up the moment you pull a listing, see the seller is paying $4,200 a year in taxes, and assume that’s your number too.

It isn’t. And the gap between what the seller pays and what you’ll pay is the single most expensive misunderstanding I see out-of-state buyers make.

Here’s how Florida property taxes, the homestead exemption, and Save Our Homes actually work, written for someone who’s never owned here before.

How Florida property taxes are calculated

Your tax bill comes from a simple formula with a few moving parts:

(Assessed value minus exemptions) times the millage rate = your tax bill.

A few things to know about each piece. Your property’s value is assessed as of January 1 each year. Florida has no state property tax, so everything you pay goes to local taxing authorities: the county, the city if you’re inside one, the school district, and various special districts. The combined rate is expressed in “millage,” meaning dollars per $1,000 of taxable value.

For Vero Beach specifically, the effective rate lands somewhere around 1% to 1.2% of market value for most homes, and it varies by where you are. Barrier island ZIP 32963 runs a bit higher, while mainland 32962 runs lower, mostly because of differences in home values and local levies. As a planning rule for a home you’re about to buy at market price, budgeting 1% to 1.5% of your purchase price is a safe starting point until you have the real numbers.

The calendar matters too. Proposed tax notices, called TRIM (Truth in Millage) notices, go out in mid-August, your window to appeal an assessment is roughly 25 days after that, and the actual tax bills are issued November 1.

The homestead exemption, and the out-of-state catch

This is the benefit everyone has heard of and almost no out-of-state buyer fully understands.

The Florida homestead exemption reduces the assessed value of your primary home before taxes are calculated. It has historically totaled $50,000, split into two parts: the first $25,000 applies to all taxes including school taxes, and the second $25,000 applies to assessed value between $50,000 and $75,000 and does not apply to school taxes. After a constitutional amendment voters approved in November 2024, the second $25,000 now adjusts upward for inflation each year, which pushed the total to about $50,722 for 2025 and $51,411 for 2026.

Now the catch, and this is the heart of “Florida homestead exemption out of state.” Homestead is only for your permanent primary residence. Only Florida residents can claim it, and to be a Florida resident you have to actually live in Florida with the intent to make it your permanent home. You cannot be claiming a residency-based exemption in another state at the same time, and you have to declare Florida as your permanent residence.

A couple of nuances that trip people up:

  • Owning a home in another state does not disqualify you. You can keep a house up north and still claim Florida homestead, as long as the Florida home is genuinely your permanent primary residence. What you can’t do is take a homestead or residency tax break in two states at once.
  • It’s about real residency, not a form you file. Filing a declaration of domicile helps establish intent, but it isn’t conclusive on its own, and if you actually live elsewhere and use the Florida home occasionally, you don’t qualify just because you signed an affidavit.

To actually get the exemption, you must own and occupy the home as your permanent residence as of January 1, and you file with the county property appraiser by March 1. You’ll typically need a Florida driver’s license and other proof of residency at the same address.

So if you’re buying a winter place and keeping your real life up north, you don’t get homestead. If you’re relocating for good, you do, and you should file the moment you’re eligible.

Save Our Homes: the benefit that quietly compounds

Homestead unlocks a second, bigger benefit over time: the Save Our Homes assessment cap.

Once your home is homesteaded, Florida limits how much its assessed value can rise each year to 3% or the change in the Consumer Price Index, whichever is lower (the 2025 cap was 2.9%). Your purchase year becomes your base year, with assessed value equal to market value, and from then on the taxable value can only creep up slowly even if the market value jumps.

Over a decade of ownership, that gap between your capped assessed value and the home’s actual market value can become large. That’s the whole reason a longtime neighbor pays a fraction of what a new buyer pays for an identical house.

If you’re selling one Florida home and buying another, there’s a bonus called portability. You can transfer up to $500,000 of your accumulated Save Our Homes savings to your new Florida homestead, as long as you establish the new homestead within three tax years of leaving the old one, using form DR-501T. This won’t apply to most first-time-in-Florida buyers, but it matters if you’re moving within the state or upgrading down here later.

The reassessment trap every out-of-state buyer needs to understand

Here’s the part I make sure every client hears before they fall in love with a number on a listing.

The seller’s low tax bill does not come with the house. When a homesteaded property is sold, that Save Our Homes cap is removed, and the property is reassessed to full market value as of January 1 of the year after the sale. Florida’s own property appraisers warn buyers directly: do not rely on the seller’s current taxes as the amount you’ll owe, because a change of ownership triggers a reassessment that can mean a much higher bill.

The longer the seller owned and homesteaded the place, the bigger the jump. If a home has been owned and homesteaded by the same person for years, your taxable value will almost certainly rise the first year after you buy, often substantially.

A quick example of how this goes wrong. You see a Vero Beach home listed at $650,000. The seller has owned it for fifteen years and is paying about $3,800 a year because their assessed value is frozen way below market. You assume $3,800. But the year after you close, the county resets the assessed value to roughly your $650,000 purchase price, and your bill comes in closer to $7,000 to $9,000 depending on location and whether you qualify for homestead. Nobody lied to you. The listing tax figure was just the seller’s number, not yours.

So when you’re evaluating a Vero Beach home, ignore the seller’s current taxes. Estimate your own bill off the purchase price and your own exemption status. This is exactly the kind of math I run for clients before they make an offer, because it can swing whether a house actually fits the budget.

What if it’s a second home? The snowbird math for the Florida homestead exemption

Plenty of my buyers aren’t relocating, they’re buying a place to escape January. If that’s you, here’s your reality:

  • No homestead exemption and no 3% Save Our Homes cap, because the home isn’t your primary residence.
  • You’ll pay roughly the full effective rate on your purchase price, so use that 1% to 1.5% planning range and lean toward the higher end on the barrier island.
  • You do still get one layer of protection. Florida caps annual assessment increases on non-homestead property at 10% a year (this cap applies to county, city, and special district levies, but not school taxes). It’s not as strong as the homestead cap, but it keeps your assessed value from tracking a hot market dollar for dollar after your first year.
  • And you still pay zero state income tax on your income, which is usually the bigger financial story for snowbirds anyway.

If you later decide to make Vero Beach your full-time home, you can convert to homestead at that point, file by March 1, and start your own Save Our Homes clock.

What’s on the November 2026 ballot (and why you should care)

This is moving as I write, so treat it as proposed, not law. There’s a property tax package headed to Florida voters in November 2026 that would meaningfully change the math, and it needs 60% approval to pass.

The headline proposal, nicknamed “Save Our Homes from Excessive Property Taxes,” would raise the homestead exemption to $150,000 in 2027 and $250,000 in 2028 for all non-school levies, indexed to inflation starting in 2029. That’s a large jump from today’s roughly $51,000.

Two pieces in the related legislative analysis are especially relevant if you’re buying from out of state. One would create a five-year homestead-style exemption on the first $50,000 of assessed value for property owners who are not permanent Florida residents as of the end of 2026, and another would lower that non-homestead assessment cap from 10% to 5%.

Again, none of this is settled, and ballot language can change. But if you’re weighing a purchase timeline, it’s worth knowing that the rules for both primary and second homes could shift after November. I’m tracking it, and I’ll tell you straight where things land.

What you need to know about the Florida homestead exemption for out-of-state owners

Florida property taxes reward residents who put down real roots and reset for everyone who buys in. The homestead exemption and Save Our Homes are genuinely valuable, but only on a primary residence, and the seller’s frozen tax bill is one of the most misleading numbers on any listing.

Before you make an offer on a Vero Beach home, the smart move is to estimate your actual future tax bill off the purchase price and your own residency situation, not the seller’s history. That’s a five-minute conversation that has changed plenty of my clients’ offers.

If you’re thinking about buying here, whether it’s a full-time move or a winter place, reach out and I’ll run the real tax numbers on any specific home with you, alongside the insurance and everything else that goes into the true cost of owning in Vero Beach.

If you’d like to speak with a human about how the Florida homestead exemption works for out-of-state buyers, feel free to contact us.
The Best Vero Beach Communities For Snowbirds

The Best Vero Beach Communities for Snowbirds: A Local Agent’s Honest Guide

  • Snowbird communities in Vero Beach fall into three lanes: barrier island golf and beach clubs at the top (John’s Island, Orchid Island, Windsor, The Moorings), mainland gated golf in the middle (Grand Harbor, Bent Pine, Indian River Club), and value-priced 55+ and condo communities (Harmony Reserve, Del Webb, Vista Royale).
  • The club membership is often a bigger decision than the house. John’s Island runs roughly $375,000 to join on top of the real estate, and Windsor’s golf equity is around $200,000, so budget for the buy-in before you fall in love with a floor plan.
  • If you’ll only be here November through April, lock-and-leave matters more than square footage. Condos and villas with exterior maintenance included beat a big single-family home you have to worry about all summer.
  • You can do the Vero Beach snowbird lifestyle well from about $250,000 in an established condo community to $20 million on the oceanfront. The right answer depends on golf, budget, and how much house you want to maintain from 1,200 miles away.

I get some version of this call every October. Someone from New Jersey or Ohio or Michigan has spent a week here, decided Vero Beach is the place, and wants to know which community to buy in. Then they tell me the list they’ve built from Zillow, and half of it is wrong for them. Not because the communities are bad, but because nobody explained the club membership math, the rental restrictions, or what it’s like to own a big house here when you’re in Cleveland from May to October.

So this is the guide I wish I could hand every snowbird before they start touring. I’m a licensed Florida real estate agent, I live here year-round, and I’ll give you the same straight version I give clients: the three lanes snowbirds actually shop in, what each one really costs, and the membership fine print that trips people up after they’ve already bought the house.

If you’re still deciding whether Vero Beach is your town at all, start with my complete relocation guide and come back. And if you want the full map of every neighborhood, not just the snowbird favorites, I keep a running guide to Vero Beach communities as well.

Lane one: the barrier island club communities

This is the Vero Beach that shows up in the golf magazines. East of the Indian River Lagoon, on the barrier island, you’ll find a handful of private club communities that are genuinely among the best in Florida.

John’s Island is the anchor. It sits in Indian River Shores just north of Vero proper, capped at 1,380 properties across roughly 1,650 acres, with three championship courses by Pete Dye, Jack Nicklaus, and Tom Fazio, plus an oceanfront beach club on about three miles of private beach. Membership is by invitation, it’s a member-owned equity club, and the all-in cost to join runs around $375,000 between the equity piece and the capital contribution. That’s on top of the house. Homes range from condos to oceanfront estates well into eight figures. One genuinely unusual perk: the vertical membership structure lets members’ parents, kids, and grandkids use the club without extra fees, which is why you see three generations of the same family here every Christmas. I’ve written a full John’s Island community guide if this is your lane.

Orchid Island Golf & Beach Club is smaller and quieter, with only 376 residences on 600+ acres running ocean to river, an Arnold Palmer course, and West Indies architecture that actually holds together as a neighborhood. If John’s Island feels like a small town, Orchid feels like a private resort.

Windsor is the design-world darling, a 425-acre new urbanist village of around 350 homes with a Robert Trent Jones links course and equity memberships that run about $200,000 for golf and $100,000 for social. It’s beautiful and it knows it.

The Moorings and Sea Oaks round out the island for buyers who want club life at a lower entry point. The Moorings sits on the south beach with yacht and country club amenities and a mix of condos, villas, and estate homes. Sea Oaks is tennis-first with a private beach club, and its villas and condos are some of the most sensible snowbird buys on the island.

The honest read: if you golf seriously and plan to spend five or six months a year here, these communities are worth every penny because the club becomes your social life. If you golf twice a winter, you’re paying a country club premium for a beach you can access from a lot of other addresses.

Lane two: mainland gated golf communities

Cross the bridge and prices drop meaningfully while the golf stays legitimate.

Grand Harbor is the one I show snowbirds most, because it covers the widest range. It’s a gated golf and beach club community on the mainland side of the lagoon with two courses, a marina, a 32,000 square foot clubhouse, and its own beach club over on the island. Condos start around $400,000, resale homes run from there up to several million, and new construction in neighborhoods like The Reserve now starts in the high six figures and climbs past $1.8 million. Club membership is separate from the real estate, and there are tiers, so you can buy the condo and take a social membership without swallowing a full golf equity buy-in. My Grand Harbor community guide breaks down the neighborhoods inside the gates.

Bent Pine is the pure golfer’s play: a classic course community west of town where the golf pedigree exceeds the price point. Indian River Club is similar, an Audubon-certified course with a friendly membership and homes that cost a fraction of the island clubs. Pointe West gives you a traditional neighborhood feel with golf attached and some of the most affordable single-family homes in any Vero golf community.

The mainland trade-off is simple: you give up walking to the beach and you gain two things snowbirds consistently underestimate, which are newer concrete block construction and lower insurance costs. When you’re writing the homeowners insurance check from Pennsylvania in August, that second one matters.

Lane three: 55+ and value condo communities

This is the lane the luxury-focused sites ignore, and it’s where a huge share of actual snowbird transactions happen.

Harmony Reserve is the standout newer option, a gated 55+ community built from 2015 onward with a resort pool, eight lighted pickleball courts, and single-family and attached homes that have been trading around $470,000 to $525,000. It’s the community I recommend when someone wants new-ish construction, real amenities, and no club buy-in.

Del Webb has active adult product in the area with single-family homes starting in the mid $400,000s, and the broader Waterway Village corridor gives you DiVosta-built gated living with clubhouses, pools, and pickleball at similar money.

Then there’s the established condo tier: Vista Royale, Vista Plantation, Vista Gardens, and Village Green. These are older communities, mostly 1970s and 1980s construction, and the units are modest. But you can still get into some of them in the $150,000 to $250,000 range, many include golf or serious amenities in the fees, and they are ruthlessly practical snowbird machines: lock the door in April, drive north, and the association handles the exterior all summer. Across Vero’s 55+ communities as a whole, average pricing sits around the mid $300,000s, which tells you how much room this lane has under the club communities.

The catch in this tier is fees and rules. Older condo associations carry rising insurance and reserve costs, and many have minimum lease terms and approval processes. Read the budget and the rental rules before you write the offer. I do this with clients on every condo deal here, because a bargain unit in a badly funded association is not a bargain.

The club membership fine print nobody explains

Here’s the part that separates a good snowbird purchase from an expensive lesson. In Vero’s club communities, the house and the club are usually separate transactions, and the club side has its own rules:

  • Equity buy-ins are real money and often non-refundable. John’s Island is roughly $375,000 to join. Windsor is $200,000 for golf equity. These are not deposits you get back at closing when you sell.
  • Membership can be by invitation, with waits. At the top clubs you don’t simply buy a house and receive a membership. There’s a process, and at times there’s scarcity, especially for full golf.
  • Some communities effectively require membership, some don’t. Grand Harbor’s tiered structure gives you options. Others tie a minimum social membership to the deed. Ask before you offer, not after.
  • Dues are a permanent line item. At the top clubs, annual dues can run well into five figures. Budget them like a second HOA.

None of this is a reason to avoid the club communities. It’s a reason to price the whole picture, house plus buy-in plus dues plus insurance, before you compare a $900,000 club home against a $500,000 non-club home and think you’re comparing like with like.

Condo, villa, or house? The six-months-away test

My rule for snowbirds is the six-months-away test: whatever you buy, you have to be comfortable leaving it alone through an entire Florida summer, including hurricane season.

Condos and villas with association-maintained exteriors pass the test easily. A single-family home passes if it’s newer concrete block construction with impact glass and you’re willing to pay for a home watch service, roughly $40 to $100 a visit here, plus landscaping and pest control while you’re gone. A big older home on the island with original windows fails the test for most people, no matter how good the price looks.

This is why so many first-time snowbirds start in a condo at The Moorings, Sea Oaks, Grand Harbor, or the Vista communities, then trade up to a house once they’ve decided Vero is a forever thing. It’s also why I’ll sometimes talk a buyer out of the bigger house they can technically afford. The right snowbird property is the one you never think about from Ohio.

How to actually choose

Strip away the marketing and the decision comes down to four questions:

  1. How much do you golf? Serious golfers belong in the club lanes. Everyone else is buying an expensive amenity they won’t use.
  2. Island or mainland? Island gets you the beach walk and the prestige. Mainland gets you newer construction, lower insurance, and more house per dollar.
  3. What’s your all-in budget? House plus buy-in plus dues plus insurance plus a summer of home watch. Run that number for each community and the field narrows fast.
  4. How long is your season? Five or six months justifies club life. Ten weeks in a condo probably doesn’t.

Every community in this post can be the right answer for the right buyer. The mistake is starting from the listings instead of starting from these questions.

Come see it in season

Photos don’t tell you what a community feels like in February, when the season is in full swing and the clubhouse parking lot is full. If you’re planning a scouting trip, come between January and March, tour at least one community from each lane, and see which version of the lifestyle actually fits. While you’re here, my local’s list of things to do will fill the hours between tours.

I help snowbirds do exactly this every winter, including the unglamorous parts like reading condo budgets and getting straight answers on membership availability. If you want the local read on any community in this post, get in touch or call or text me at (772) 999-4457. No pressure and no spam. You can also start at jonsterling.com to see how I work.

Related reading

South Beach Vero Beach: A Local’s Down-To-Earth Guide

Is Vero Beach South a nice place to live?

  • South Beach is the quiet southern stretch of the Vero Beach barrier island, below the 17th Street Causeway, inside the 32963 ZIP code. It trades Central Beach’s walk-to-dinner energy for calmer streets and more house for the money.
  • The communities range from gated club living at The Moorings to deeded-beach-access family neighborhoods like Castaway Cove, plus river-access boating pockets and a wide band of condos. Prices run from the low $300s for older condos to well past $5M for oceanfront estates.
  • The number that surprises buyers is not the price. It’s the carrying cost. Insurance, flood coverage, HOA dues, and club fees can move your real monthly payment by thousands, and most listing pages never mention it.
  • South Beach fits families, boaters, and buyers who want a calm, established neighborhood. It’s the wrong fit if you want to walk to nightlife or you’re shopping purely on sticker price.

If you’ve been reading neighborhood pages that call South Beach “the best of both worlds” and leave it there, you’re not getting the part that actually decides whether you’ll be happy here. I sell on this island. Let me give you the version with the trade-offs left in.

South Beach is where a lot of relocating families and second-home buyers end up once they realize Central Beach is pricier and busier than they pictured, and the mainland feels too far from the sand. It sits in the middle of those two worlds, and that middle is exactly why it works for so many people. It’s also why a few buyers end up in the wrong house here, which I’ll get to.

Where South Beach actually is

South Beach is the southern third of the Vero Beach barrier island. The rough boundary in most people’s heads is the 17th Street Causeway (the Alma Lee Loy Bridge). North of it you’re heading into Riomar and Central Beach. South of it, the island gets quieter, more residential, and more spread out the farther you go toward the south end.

The whole area sits in 32963, the barrier-island ZIP code, with the Atlantic on one side and the Indian River Lagoon on the other. That two-water geography matters more than it sounds. It’s why some South Beach homes have deeded ocean access while others, just a few streets west, have a boat dock on the lagoon. Same neighborhood label, completely different lifestyle and price. If you want the bigger picture of how the island and mainland fit together, I broke that down in my guide to where Vero Beach actually is.

A1A (Ocean Drive as it runs south) is the spine. South Beach Park, a lifeguarded public beach, anchors the area and is one of the better spots on the island for families who want sand without a club membership.

vero beach south

What living in South Beach feels like day to day

Quiet is the headline. A lot of the streets are dead-ends or low-traffic loops, which is why families gravitate here. Kids ride bikes, neighbors know each other, and the pace is closer to a residential coastal town than a beach resort.

You’re still close to everything. A short drive or bike ride puts you in the Central Beach village for dinner, the Saturday vibe, and the shops, and the mainland’s groceries and big-box stores are over the causeway. You get calm at home and convenience nearby, without paying the Central Beach premium to live on top of the restaurants. If you want a running list of what there is to do once you’re settled, I keep a local’s guide to things to do in Vero Beach updated.

The honest flip side: this is not a walk-to-nightlife neighborhood, and Vero in general winds down early. If your idea of beach living is strolling to a bar at 10pm, South Beach will feel sleepy. That’s a feature for most of my buyers and a dealbreaker for a few. Know which one you are before you fall for a house here.

The communities, by what you actually get

The competitor pages love to drop a comparison table as an image and move on. Here’s the real breakdown in plain text, organized by what kind of buyer each one fits.

The Moorings. The marquee club community at the south end. A Pete Dye championship golf course, a full marina, and a private club-maintained beach. This is country-club living, and it’s priced and structured accordingly. Worth it if you’ll actually use the golf, the boating, and the social side. If you won’t, you’re paying club dues for amenities you’ll watch other people enjoy.

Castaway Cove. One of the most popular family neighborhoods on this part of the island. Gated, with the recognizable winding street layout and, importantly, private deeded beach access for residents. This is the sweet spot for a lot of families who want security and ocean access without a full club membership.

Sea Oaks. A gated oceanfront community with its own beach club, tennis, and a more amenity-rich, condo-and-villa mix. Popular with seasonal owners and buyers who want lock-and-leave convenience near the sand.

Sandpointe and Seagrove. Established residential pockets that give you South Beach location and a more traditional neighborhood feel, often at a lower entry point than the marquee clubs.

River and lagoon-side boating communities. On the western side of A1A, areas with deep-water access give boaters direct routes to the Intracoastal. If your priority is a dock and a boat more than your toes in the ocean every morning, this is the side of the neighborhood to focus on.

Condos. South Beach has a deep band of condos, from older 1970s and 1980s buildings to renovated units, that are the real affordable entry into 32963. This is how plenty of people get a barrier-island address without a single-family-home budget.

What your money actually buys

I’ll talk in tiers instead of exact numbers, because exact numbers go stale fast and the last thing you want is a blog post quoting a price that was right six months ago.

Entry tier, roughly low $300s to mid $400s: older condos and smaller units. This is your foothold on the island.

Mid tier, roughly $500s to low $1M: single-family homes in the established residential pockets, nicer condos, and villas in the amenity communities. This is the heart of the market for relocating families.

Upper tier, $1M and well beyond: gated-community homes, club properties, and anything with real ocean proximity. Oceanfront and large estates run several million and up.

The mistake I see most often is a buyer anchoring on the list price of a mid-tier home and budgeting from there, without running the rest of the math. That’s the section nobody else will write for you, so here it is.

The part listing pages skip: insurance, flood, and club fees

This is where I earn my keep and where the thin neighborhood posts go silent.

Insurance. Florida’s property insurance market has been rough, and barrier-island homes feel it. A windstorm policy on an older South Beach home can be a serious line item, and it varies enormously by the home’s age, roof, and wind-mitigation features. Two houses on the same street can have very different premiums. Get a real quote before you’re under contract, not after.

Flood. Two-water geography means flood zones matter. Some South Beach properties sit in higher-risk zones that require flood insurance, and the premium depends on elevation and the specific property. This is checkable up front, and you should check it before you write an offer, not during inspection.

HOA and club fees. A gated community has HOA dues. A club community layers club membership and dues on top, and those can run into real monthly money. The Moorings is a different financial animal than a non-club neighborhood two miles north. When you compare two homes, compare the all-in monthly number, not the price.

Add those three together and your real monthly cost can swing by thousands between two homes that looked similar on Zillow. When you’re ready to actually make a move on a place, my reasonable offer chart walks through how to think about what to offer once you have the full cost picture in front of you.

South Beach vs Central Beach vs North Beach

Most buyers comparing these three are really choosing between three different daily lives.

Central Beach is the village. Walkable, more shops and restaurants, more energy, and you pay for the location and walkability. Pick it if proximity to dinner and the social scene is the point.

South Beach is the calm, residential middle. More house and more yard for the money, family-friendly streets, club options if you want them, and a short drive to Central Beach when you want the buzz. Pick it if you want a neighborhood, not a strip.

North Beach runs the gamut from the ultra-exclusive enclaves up toward Indian River Shores and beyond, to quieter residential stretches. It tends to feel even more removed and, at the top end, more private and pricey.

If you’re weighing the island against other Florida beach towns entirely, I put Vero head to head with another popular pick in Vero Beach vs Cocoa Beach, which covers the same kind of trade-offs at the city level.

Who South Beach is right for (and who should look elsewhere)

South Beach is a strong fit if you’re a family that wants safe, quiet streets and beach access without living in the middle of the action. It’s great for boaters who want lagoon and Intracoastal access. It works for seasonal owners who want a lock-and-leave condo or villa in an amenity community. And it’s right for buyers who want more square footage and yard than the same budget gets you in Central Beach.

Look elsewhere if you want to walk to nightlife and restaurants every night, if you’re shopping strictly on the lowest sticker price and won’t budget for island insurance and dues, or if a club community’s fees would stretch you to afford amenities you won’t actually use. There’s no shame in any of that. It just means a different neighborhood, or a different part of the island, fits your life better.

South Beach Vero Beach FAQ

Where is South Beach in Vero Beach?
It’s the southern section of the Vero Beach barrier island, generally south of the 17th Street Causeway, in the 32963 ZIP code, with the Atlantic Ocean to the east and the Indian River Lagoon to the west.

Is South Beach a good place for families?
Yes. The quiet, low-traffic streets and communities with deeded or club beach access, like Castaway Cove and Sea Oaks, make it one of the more family-oriented parts of the island.

Can you get a home on the barrier island affordably in South Beach?
The most affordable entry is the older condo market, which can start in the low $300s. Single-family homes generally start higher and climb quickly with ocean proximity and gated-community status.

Does South Beach have boating access?
Yes. Communities on the western, lagoon side of A1A offer deep-water docks with direct access to the Intracoastal Waterway, while The Moorings has a full marina.

What’s the catch with buying in South Beach?
The carrying cost. Insurance, flood coverage, and HOA or club fees can change your real monthly payment dramatically, so always compare the all-in number, not just the list price.

Thinking about South Beach? Let’s talk before you tour.

Tell me three things: your budget, whether you want ocean access, club living, or a boat dock, and whether this is a full-time move or a seasonal place. I’ll send you the South Beach homes that actually fit, with honest insurance and fee estimates attached so the monthly number you’re picturing is the real one. Get in touch here or call or text me, day or night, at (772) 999-4457. Straight answers, no drip campaign you can’t escape.

If you’re relocating from out of the area, start with my complete Vero Beach relocation guide for the full cost-of-living, schools, and market picture.

Related reading about Vero Beach South, and the rest of Vero Beach

How to Choose A Realtor In Florida: What Separates the Good Ones

Overview of how to choose a Realtor in Florida

  • Most people pick a Realtor based on who they already know or who has the biggest billboard, and that’s exactly how you end up with the wrong one.
  • The four things that actually matter are full-time production, real market knowledge in your price band, negotiation track record, and whether the agent will tell you the truth when it costs them a commission.
  • Interview at least two agents, ask them direct questions, and pay attention to whether they answer with specifics or with slogans.
  • I spent years on the hiring side of this business, training and managing thousands of agents, so I can tell you the difference between an agent who looks good and one who closes well.

Figuring out how to choose a Realtor in Florida is tricky. Almost everyone does it backwards. They use the agent who sold their cousin’s house, or the friendly face from a bus bench ad, or the first name that pops up on Zillow. Then they hand that person the biggest financial transaction of their life and hope it works out.

I have a different vantage point on this than most agents. Before I was selling homes here on the Treasure Coast, I helped launch Keller Williams in the United Kingdom and later ran operations as an area director overseeing dozens of offices and roughly 7,000 agents in South Florida. I have hired, trained, coached, and yes, let go of more agents than most buyers will ever meet in a lifetime. So when I tell you what separates a good Realtor from a forgettable one, it is not theory. I watched it play out across thousands of careers.

Here is what to actually look for.

Choose a Realtor who is full-time and producing, not part-time and hoping

For my statistics fans: Did you know the average Realtor only sells three houses a year? And they never release the median number of houses an agent sells in a year (because it’s probably a zero).

The first filter is the simplest and it eliminates most of the field. Is this person doing real estate full-time, and are they closing deals consistently?

There is nothing wrong with people who sell a few houses a year on the side. But a part-time agent is learning on your transaction. They do not have the rep volume to spot a problem inspection report before it blows up your closing, or to know what a lowball offer really means versus a serious one. Real estate is a pattern-recognition job. You want someone who has seen the patterns enough times to react fast.

Ask the question directly: “How many transactions did you close in the last twelve months?” You are not looking for a record-setting number. You are looking for steady, real activity. An agent who closes one or two homes a year is not in the same job you think you are hiring for.

Knowledge of your specific market and price band

“Local knowledge” gets thrown around so much it has lost meaning. Let me make it concrete.

A great Vero Beach agent does not just know “Vero Beach.” They know that the barrier island and the mainland are two different markets with different buyers. They know which communities have HOA rules that scare off certain buyers, which streets flood, which neighborhoods are quietly appreciating, and what a fair price per square foot looks like this month in your exact area and price range.

That last part matters more than people realize. An agent who lives in the $400,000 market all day may not understand how a $1.5 million barrier island sale actually moves, who the buyers are, and how long it sits. The reverse is true too. When you interview an agent, ask them to walk you through three recent sales in your neighborhood and price band, and listen for whether they can talk about them in real detail or whether they pull up Zillow and read you the numbers you could have read yourself.

If you are moving here from out of state, this gap is even bigger, because you do not yet have the local context to catch an agent who is bluffing. That is part of why I built out a full relocation guide for people moving to Vero Beach, so you walk into those conversations already knowing what good looks like.

How to choose a Realtor with a real negotiation track record

This is the skill people undervalue most, and it is the one that actually puts money in your pocket or takes it out.

Anyone can fill out a contract. Negotiation is a different muscle. It shows up in how an agent handles a multiple-offer situation, how they respond to a seller who counters high, how they protect your earnest money, and how they keep a deal together when the inspection turns up a $12,000 surprise. A weak negotiator either folds to keep the peace or blows up the deal trying to win. A strong one finds the path that gets you the home at terms you can live with.

I learned negotiation the hard way, across deals on three continents and through markets that were booming and markets that were falling apart. If you are interviewing an agent, ask them to tell you about a deal that almost fell through and how they saved it. The good ones light up at that question, because saving deals is the part of the job they are proud of. The weak ones get vague.

If you are weighing a cash purchase or wondering how cash offers really compete here, that is a negotiation question too, and I broke down how it works locally in my piece on Vero Beach cash buyers.

Will they tell you the truth when it costs them?

Here is the real test, and almost no buyer thinks to apply it. If you want to know how to choose a Realtor in Florida, this might be the most important piece.

A great Realtor will talk you out of a house. They will tell you the kitchen renovation you are excited about will not return the money. They will say “this one is overpriced, let’s wait” even though waiting means they do not get paid this month. The whole business runs on commission, which means the easy move is always to nudge you toward yes. The agents worth hiring resist that, because they are building a career on referrals, not a quick paycheck.

When you interview someone, float a slightly bad idea on purpose. Mention a house that is clearly above your budget, or a fixer-upper you have romanticized. Watch whether they cheer you on or gently push back. The pushback is the green flag. An agent who only ever agrees with you is not protecting you, they are managing you.

How to run the interview

Choosing a Realtor should feel like hiring for a job, because it is one. Talk to at least two agents before you commit. Ask each of them:

  • How many homes did you close in the last year, and how many were buyers versus sellers like me?
  • Tell me about three recent sales in my area and price range.
  • Walk me through a deal that almost died and how you kept it alive.
  • What would you tell me not to do right now?
  • How and how often will you communicate with me?

That last one matters more in practice than people expect. Plenty of competent agents lose clients simply because they go quiet for days at the worst possible moments. You want to know upfront whether you are getting a text back in an hour or an email back next week.

Then check the basics. Look at real reviews, not just the testimonials on their own site. Make sure their license is active and clean. And trust your read on whether this is someone you actually want in your corner for the next sixty to ninety days, because you are going to be in close contact through some stressful moments.

The quick synopsis on how to choose a Realtor in Florida

You do not need the agent with the most billboards or the flashiest Instagram. You need a full-time professional who knows your market cold, can negotiate, and will tell you the truth even when it costs them. Run the interview, ask the hard questions, and the right person becomes obvious fast.

I will say plainly that I think I am a strong fit for a lot of buyers and sellers here, and the reasons are exactly the ones above. You can read more about my background and how I got to Vero Beach on my about page, and if you want to put me through the same interview I just told you to run on everyone else, I would welcome it. That is the whole point.

When you are ready to talk, reach out here. No pressure and no hard sell, which, now that you have read this far, you already know is not how I work. You can also start at the homepage to see what I’m working on across the Vero Beach market.

Related reading

What Is Central Beach in Vero Beach?

What Is Central Beach in Vero Beach? A Local Agent Explains

  • Central Beach is the walkable heart of Vero Beach’s barrier island, roughly the grid of streets between the Atlantic Ocean and the Indian River Lagoon surrounding Ocean Drive and Beachland Boulevard.
  • The residential streets are named after flowers and trees in alphabetical order (Acacia, Banyan, Camelia, Cypress, and so on), which is the fastest way to know you’re in Central Beach.
  • It’s not a gated community and there’s no HOA for most of it. It’s an old-fashioned neighborhood where you can walk or take a golf cart to the beach, restaurants, and shops.
  • Homes range from 1950s cottages around $1M to oceanfront estates well north of $10M, with condos offering lower entry points along Ocean Drive.
  • The tradeoffs are real: older housing stock, coastal insurance costs, and seasonal crowds. For the right buyer, none of that matters.

If you’ve spent any time researching Vero Beach real estate, you’ve seen the phrase “Central Beach” everywhere. Listings mention it. Locals reference it constantly. But nobody seems to define it, because it’s not a gated community, a subdivision, or a legal designation. It’s a neighborhood in the truest sense of the word, and after years of showing homes here, I can tell you it’s the most requested area on the barrier island by a wide margin.

So let’s answer the question.

Central Beach, defined

Central Beach is the walkable core of Vero Beach’s barrier island. Roughly speaking, it’s the grid of residential streets that sits between the Atlantic Ocean and the Indian River Lagoon, wrapped around the Ocean Drive and Beachland Boulevard commercial district. The Barber Bridge (Merrill P. Barber Bridge, if we’re being formal) drops you right into it from the mainland.

There’s no gate, no guardhouse, and for most of the neighborhood, no HOA. That alone separates it from most of the barrier island. Communities like John’s Island and The Moorings are club communities with membership structures and gated entries. Central Beach is just a neighborhood. You buy a house, you get keys, you walk to the beach. That simplicity is a big part of the appeal.

The alphabetical streets

Here’s the local shorthand for knowing you’re in Central Beach: the residential streets are named after flowers and trees, and they run in alphabetical order. Acacia, Azalea, Banyan, Bougainvillea, Camelia, Cypress, Date Palm, and on down the alphabet as you move through the neighborhood. Add in streets like Live Oak and Greytwig and you’ve got the picture.

It sounds like trivia, but it matters for buyers. When a listing says “the flower streets” or “the tree streets,” that’s Central Beach, and it usually signals the quieter residential blocks a short walk from Ocean Drive rather than the oceanfront itself. Those blocks are where you find the classic Central Beach product: older single-story homes on mature, oak-canopied lots.

What daily life actually looks like

The reason people pay a premium for Central Beach is compression. Everything is close together in a way that almost nothing else in Florida is.

Humiston Beach Park anchors the ocean side, with the Saturday farmers market running right there in season. Ocean Drive is a genuine walkable business district: independent boutiques, coffee, galleries, and restaurants in a few compact blocks, not a strip mall pretending to be one. Waldo’s at the historic Driftwood Resort has been the beachside institution for decades. A few minutes over the bridge or up the island you have the Vero Beach Museum of Art and Riverside Theatre, which both punch way above what a town this size should have.

The neighborhood is also golf-cart friendly, and plenty of residents treat the cart as the primary vehicle. School run, dinner, beach, market, all without touching a car. If you’ve read my complete Vero Beach relocation guide, you know I’m generally allergic to lifestyle marketing language, but Central Beach genuinely delivers the “walk to everything” promise that gets thrown around loosely everywhere else.

What homes cost in Central Beach

This is where most “what is Central Beach” content goes quiet, so here’s the honest version.

Interior streets (the flower and tree streets): Older cottages and mid-century homes generally start around $1M, with renovated and newer-construction homes running $2M to $5M or more depending on lot, finish, and proximity to the beach. Teardowns and major remodels are common because the land is worth more than a lot of the original 1950s and 1960s structures sitting on it.

Oceanfront: Limited supply, serious money. Oceanfront homes along Ocean Drive trade well into eight figures, with trophy properties listing at $10M to $35M.

Condos: The most attainable way into the neighborhood. Low-rise and mid-rise buildings along and near Ocean Drive offer lock-and-leave living at price points meaningfully below the single-family market, with HOA fees and building rules attached.

If you want the deeper breakdown of housing stock, buyer fit, and how Central Beach compares to the rest of the island, that lives on my full Central Beach neighborhood guide.

The tradeoffs nobody mentions

I sell homes here, and I’ll still tell you the downsides, because the buyers who love Central Beach love it with eyes open.

The housing stock is old. A lot of it is charming old, but old means insurance carriers ask hard questions about roofs, wiring, and wind mitigation. Budget for coastal insurance and, on many homes, budget for updates.

Flood and wind exposure are part of barrier island life. Elevation and flood zone vary block by block. This is exactly the kind of thing your agent should pull before you fall in love with a house, not after.

Season changes the neighborhood. From roughly Thanksgiving through Easter, Ocean Drive parking tightens up and restaurant waits get real. Locals adjust their routines. If crowds ruin a place for you, visit in February before you buy.

No HOA cuts both ways. You get freedom, and so does your neighbor with the boat trailer.

How Central Beach fits the rest of the island

Quick orientation for anyone comparing neighborhoods: Central Beach is the unstructured, walkable option. If you want gates, golf, and club life, you’re looking at communities like John’s Island, The Moorings, Orchid Island, or Riomar instead. If you want the beach lifestyle without membership commitments, Central Beach is usually the answer. I keep a running comparison of all of them on my Vero Beach communities page.

FAQ

Is Central Beach a gated community?
No. It’s an open neighborhood with public streets, and most of it has no HOA. That’s a feature, not a bug.

What zip code is Central Beach in?
32963, which covers Vero Beach’s barrier island.

Is Central Beach walkable?
Yes, and it’s arguably the most walkable neighborhood on Florida’s Treasure Coast. Beach, restaurants, shops, and parks are all within a few blocks of most homes.

Can you drive a golf cart in Central Beach?
Yes, golf carts are a normal part of daily life on the neighborhood streets. Follow local rules on where carts are permitted.

How much does a house in Central Beach cost?
Plan on roughly $1M as the practical entry point for single-family homes, $2M to $5M for renovated homes on the interior streets, and eight figures for oceanfront. Condos come in lower.

Thinking about buying or selling in Central Beach?

I’m Jon Sterling, a licensed Florida real estate agent based right here in Vero Beach. I walk these streets, I know which blocks flood and which don’t, and I’ll give you the straight version of what a house is worth. If Central Beach is on your list, get in touch and let’s talk it through.

Related reading

Vero Beach vs. Hutchinson Island

Vero Beach vs. Hutchinson Island: A True Comparison

  • Vero Beach and Hutchinson Island are not the same place, and they’re not even the same county. Vero’s beachside sits in Indian River County, while most of Hutchinson Island falls in St. Lucie and Martin counties.
  • That county line drives your property taxes, your school district, and a chunk of your insurance picture, which is the part most comparison articles skip entirely.
  • Hutchinson Island is condo country with a wide price range, recently around a $637,000 median. Vero’s barrier island leans toward low-rise single-family homes and established club communities, and it runs pricier at the top end.
  • The “Vero Beach Ocean Club” you may have found online is actually on Hutchinson Island near Fort Pierce, not in Vero Beach. The name is marketing, and it trips up a lot of buyers.
  • Neither one is better. They fit different lives. This guide is about figuring out which life is yours.

If you’re searching “Vero Beach vs. Hutchinson Island,” you’ve probably already noticed something confusing: some listings put “Vero Beach” and “Hutchinson Island” in the same address. So which is it? Here’s the straight answer from someone who sells here. They’re two separate barrier islands, in different counties, with different rules, different inventory, and a genuinely different feel. Picking between them isn’t a coin flip. It’s a decision about taxes, insurance, what kind of home you want to own, and how you actually plan to spend your days.

Let me walk you through it the way I would if we were sitting across a table.

First, the geography nobody explains with Vero Beach vs. Hutchinson Island

Vero Beach’s beachside is part of the barrier island in Indian River County. The City of Vero Beach caps building height on the island at four stories, so you get a low, leafy, village skyline instead of a wall of towers. This is the stretch with Ocean Drive, the boutiques, and the established gated communities.

Hutchinson Island is a separate barrier island to the south. It runs roughly 23 miles and is split into North and South sections by the Fort Pierce Inlet. The two islands are divided by the Fort Pierce Inlet and are known as North Hutchinson Island and South Hutchinson Island. Most of it sits in St. Lucie and Martin counties, anchored by Fort Pierce, Jensen Beach, and Stuart on the mainland side.

Here’s the part that catches buyers off guard. There’s a luxury enclave marketed as the “Vero Beach Ocean Club,” and despite the name, it’s physically on the north end of Hutchinson Island near Fort Pierce, in the 34949 zip code. It’s a gated Hutchinson Island community of estate homes and oceanfront residences with private beach access through an underground tunnel. The homes there are spectacular and priced to match, recently listed from around $7.5 million to $14.9 million. But if you buy there thinking you’re buying “in Vero Beach,” you’re actually buying in St. Lucie County, with St. Lucie County taxes and schools. That distinction matters, and it’s exactly why I tell people to look at the county line before they fall in love with a name.

If you want the full lay of the land, I put together a plain-English explainer on where Vero Beach actually is and how the island, the mainland, and the county fit together.

The county line is the real decision

This is the section the brochure sites leave out, and it’s the one that costs or saves you money every single year.

When you buy on Vero’s barrier island, you’re in Indian River County. Your kids are zoned for the Indian River County School District, your taxes are set by Indian River County’s millage, and your closest hospital is the Cleveland Clinic Indian River. Everything you need day to day is a short drive, and most of it is on the same island or just across the bridge.

When you buy on Hutchinson Island, you’re most likely in St. Lucie County (north end) or Martin County (south end). Hutchinson Island falls within the St. Lucie County school district on the north end. Different county means a different tax bill, a different set of schools, and different permitting and service providers. None of that is good or bad on its own. It’s just real, and you should know it before you write an offer, not after.

My honest take: if school zoning or staying inside one specific county matters to you, settle that question first. It quietly narrows the map more than price does.

What you actually buy on Hutchinson Island

The two islands sell very different products, and the price ranges reflect that.

Hutchinson Island is mostly condos, especially oceanfront mid-rise and high-rise buildings, plus pockets of single-family homes and a few ultra-luxury estates. The range is wide. On the north end, condos have recently ranged from about $265,000 up to roughly $1.6 million, with a median home price around $525,000 as of spring 2026 and homes sitting on the market about 145 days. On the south end, houses have ranged from the low $200,000s to over $7 million, with a median near $585,000. Islandwide, the median sale price was about $637,000 in May 2026, with homes taking a median of 135 days to sell. Translation: you can get on the ocean here for a lot less than you’d expect, as long as you’re open to a condo.

Vero’s barrier island is the opposite shape. It’s heavy on single-family homes, older beach cottages, and established club communities like John’s Island, Windsor, The Moorings, Riomar, Sea Oaks, and Orchid Island, with a smaller, boutique condo market because of that four-story height cap. The entry point for an island condo or an older cottage can be reasonable, but the top of the market runs well into the multimillions, and the gated golf communities carry membership and HOA costs on top of the purchase price. You can browse the full set of Vero Beach communities to see how they stack up.

If you want a tower with a wraparound balcony and panoramic ocean views, Hutchinson Island is built for that. If you want a single-family home in a low-density, manicured island neighborhood, Vero is hard to beat.

Flood and insurance: read this before you fall in love with Hutchison Island

Both islands are barrier islands on the Atlantic, so both carry real flood and wind exposure. You should budget for flood insurance and windstorm coverage in either place, full stop.

That said, the risk profile on parts of Hutchinson Island is steep. On North Hutchinson Island, roughly 97% of properties are considered at risk of severe flooding over the coming decades, which is classified as extreme flood risk. That doesn’t mean don’t buy there. Plenty of well-built, elevated, impact-rated buildings handle it fine. It means get real quotes before you’re under contract, ask how the building or home has weathered recent storms, and factor the annual carrying cost into your budget, not just the purchase price.

I’d tell you the same thing about Vero’s island, by the way. The difference is mostly in the details of the specific building or street, not a blanket “one island is safe and one isn’t.” Insurance is a per-property question here, and it’s worth answering early.

Daily life: structured charm vs. spread-out calm

This is the soft part, but it’s often what decides it.

Vero Beach gives you a self-contained life on the island. Ocean Drive is walkable, with shops, sidewalk cafes, and restaurants steps from the sand. You’ve got the Riverside Theatre and the Vero Beach Museum of Art, strong medical care, and a downtown that functions year-round. For a town its size, the culture punches above its weight. You rarely have to leave the island to live a full week.

Hutchinson Island trades that for space and quiet. It’s longer, less dense, and built around the outdoors: fishing, boating, kayaking, miles of beach, and protected stretches that are nesting grounds for sea turtles. The tradeoff is that your dining, shopping, and errands usually mean a short drive across the causeway into Fort Pierce, Jensen Beach, or Stuart. If your ideal day is a beach walk and a fishing charter rather than a gallery opening and a tasting menu, that’s a feature, not a bug.

If you’re weighing this kind of “town personality” question across the area, my Vero Beach vs. Sebastian comparison runs the same honest playbook on a different matchup.

So in the question of Vero Beach vs. Hutchinson Island, which one fits you best?

Here’s how I’d sort it.

Vero Beach is the better fit if you want a single-family home or an estate, you value a walkable downtown and real cultural amenities, you’d use top-tier medical care close by, and you like the idea of a low-rise island that’s protected from overdevelopment by that height cap. It’s also the stronger pick if staying inside Indian River County matters for schools or taxes.

Hutchinson Island is the better fit if you want oceanfront for a lower entry price, you’re happy in a condo with big water views, you live for boating and fishing, and you don’t mind driving to the mainland for dinner and errands. It’s also worth a hard look if you want more square footage of beach and a slower, more spread-out pace.

There’s no wrong answer. There’s only the answer that matches how you actually want to spend your time and your money. If you’re still torn, the smartest move is to get specific about budget, home type, and county priorities before you tour, so we’re not burning weekends looking at the wrong island.

When you’re ready to move from “researching” to “narrowing it down,” that’s where I come in. I’ll line both islands up against your real budget, get you accurate insurance numbers for the specific buildings or streets you like, and tell you honestly when one island fits you better than the other. Call or text me at 772-999-4457, or reach out through jonsterling.com, and we’ll build a plan around what you’re actually looking for. If you’re moving from out of the area, start with my complete Vero Beach relocation guide, and when it’s time to talk numbers, my reasonable offer chart will show you how to land on a smart offer.

Related reading

The Most Expensive Communities In Port St. Lucie (2026 Guide)

What Are The Most Expensive Communities in Port St. Lucie?

  • Port St. Lucie’s most expensive communities are Tesoro Club, PGA Village (especially Sabal Creek), the upscale enclaves inside Tradition, Astor Creek Golf and Country Club, Rivella, and a handful of riverfront pockets along the St. Lucie River.
  • The sticker price is not the real number. Several of these communities carry CDD bonds, mandatory club memberships, or both, and that can add hundreds to over a thousand dollars a month on top of your mortgage.
  • New construction dominates the high end here, which is great for buyers who want turnkey but means you should read the builder contract and the CDD disclosure carefully.
  • Port St. Lucie luxury still runs well below comparable Vero Beach island communities, so if you are shopping the top of this market, it’s worth driving 30 minutes north before you commit.
  • I work the whole Treasure Coast, so this list is ranked by what buyers actually pay and live with, not just by listing photos.

If you searched for the most expensive communities in Port St. Lucie, you probably found a few posts that list the same five neighborhoods, call each one “opulent,” and never tell you what it costs to actually live there. I want to fix that. I sell across the Treasure Coast, Port St. Lucie included, and the questions buyers ask me are never “which one has the nicest clubhouse.” They ask what the dues run, whether there’s a CDD bond hiding in the price, and which community fits how they actually want to spend a Tuesday. So that’s how I’m going to break this down.

How I ranked these (and why “expensive” is not just the list price)

“Expensive” in Port St. Lucie comes from three places, and you need to look at all three.

The first is the home itself, the price you see on the listing. The second is the CDD bond, which is a community development district assessment that pays off the infrastructure (roads, utilities, drainage) the developer put in. A lot of Port St. Lucie’s master-planned communities have one. It shows up on your tax bill, it can run anywhere from a few hundred to a couple thousand dollars a year, and it is on top of your regular property taxes. The third is club and HOA dues, which in the golf communities can include a mandatory membership with an initiation fee plus monthly dues.

Two homes with the same list price can cost very differently to own once you add those layers in. That’s the part the other guides skip, and it’s the part that actually decides your monthly number. I’ll flag it for each community below.

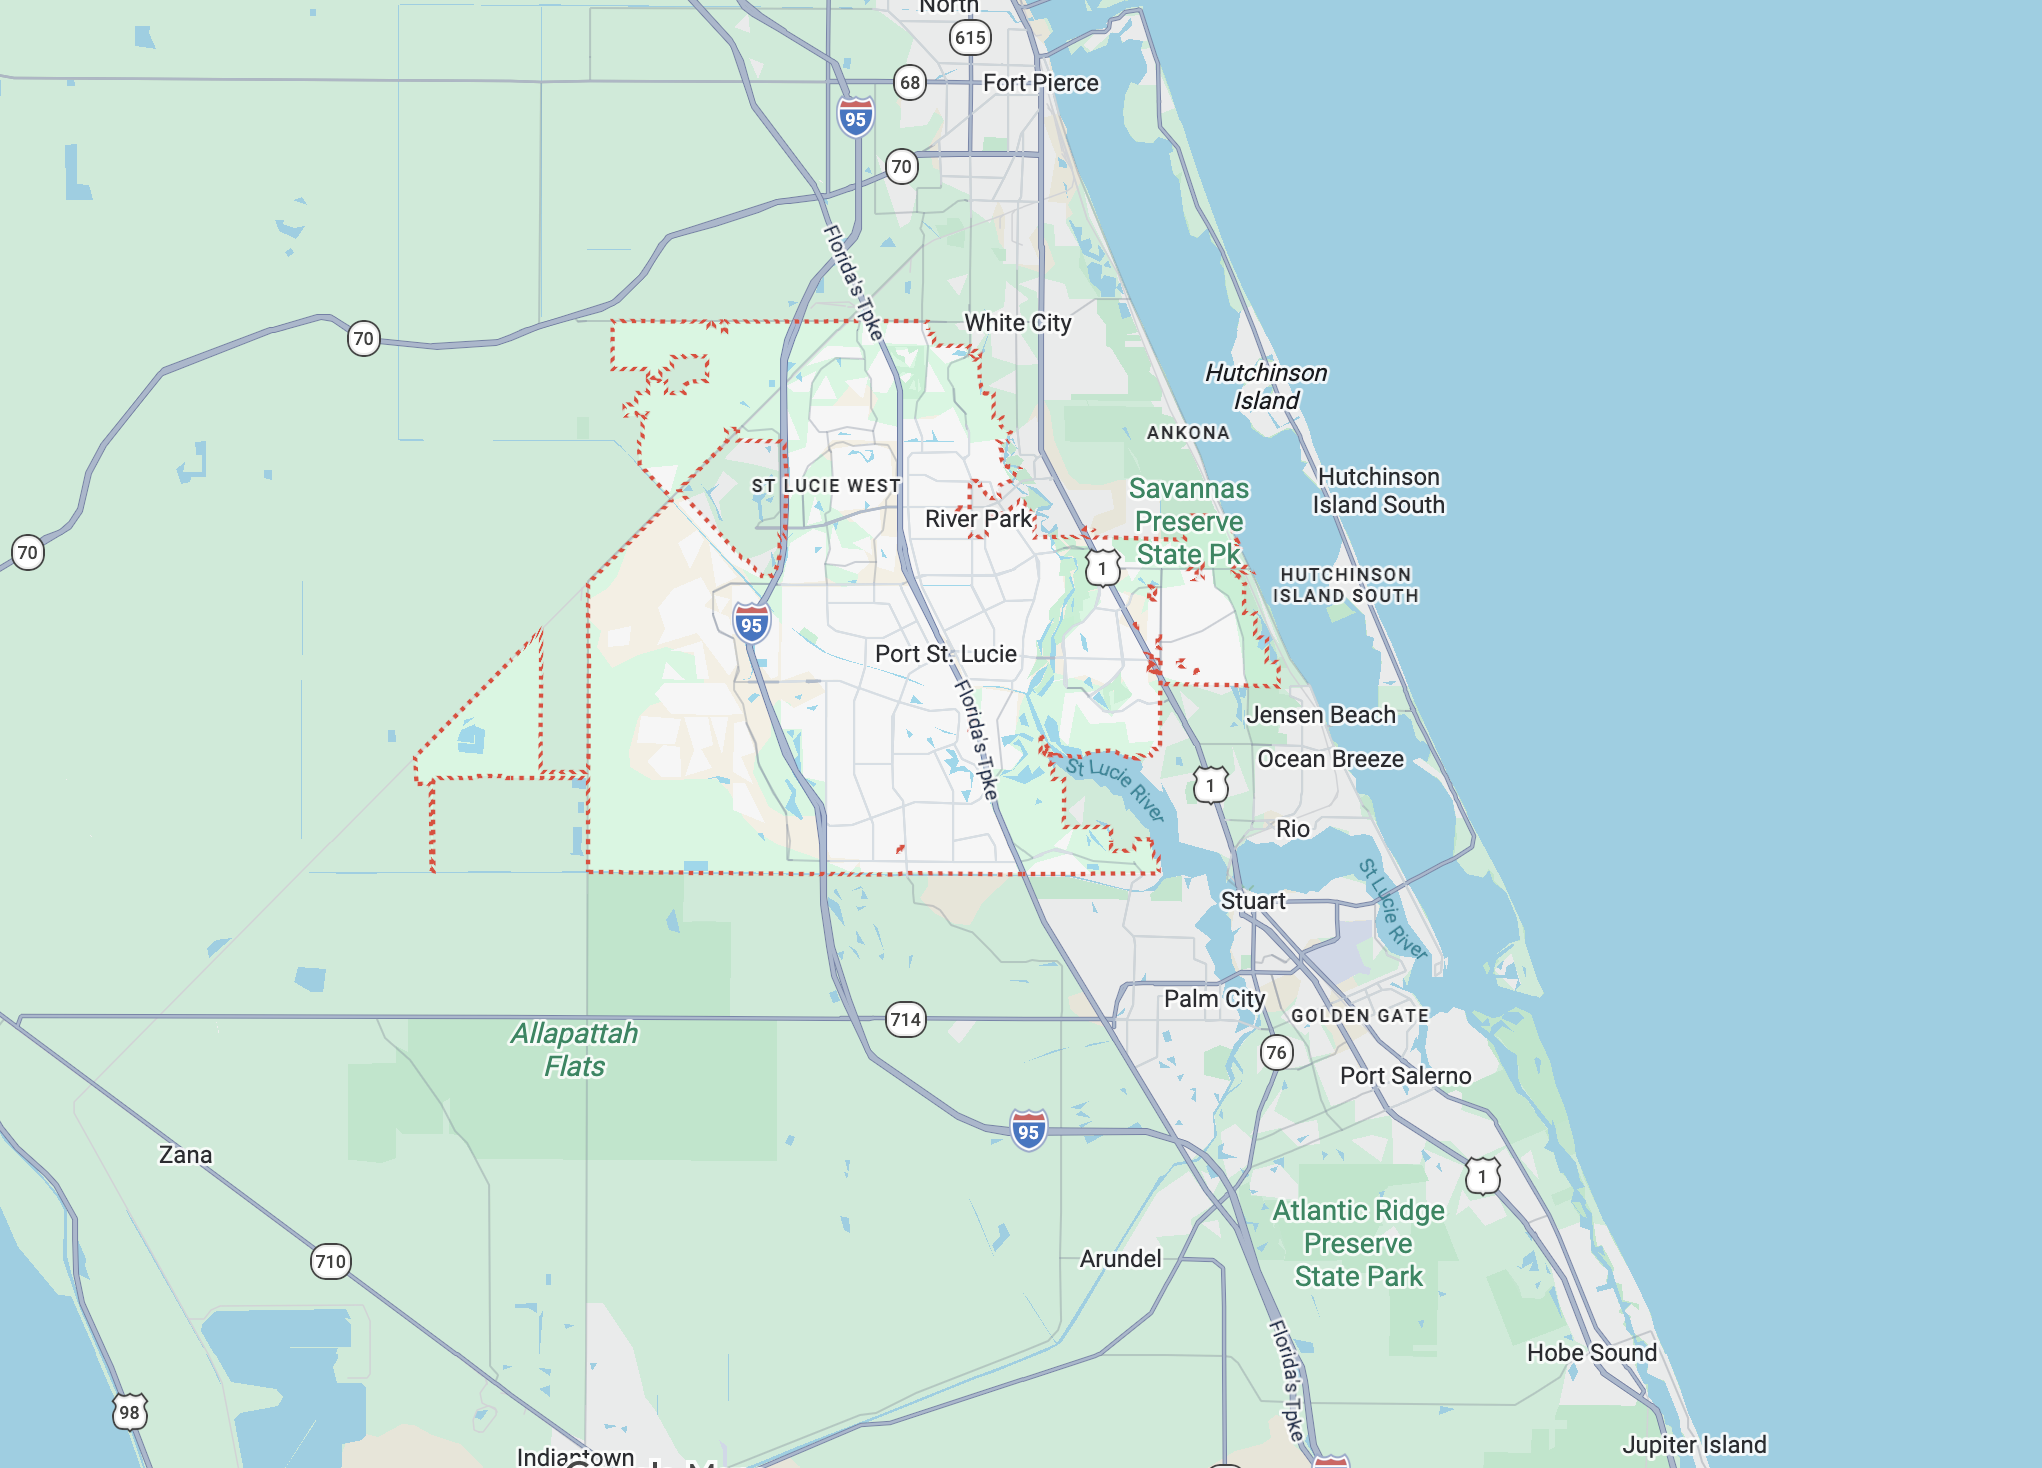
map of port st lucie florida

Where is Port St. Lucie on the map of Florida? This should help you visualize it.

Tesoro Club

Tesoro is usually the first name anyone says when they talk about luxury in Port St. Lucie, and that reputation is earned. It’s a large gated golf community off I-95 with a renovated clubhouse, two championship courses (the Palmer and Watson names get mentioned a lot), a racquet center, a spa, and a resort pool. The homes lean toward custom estates and luxury villas with Mediterranean and Florida contemporary styling.

What it actually costs: This is the top price tier in Port St. Lucie. Estate homes here regularly reach seven figures, and resale inventory is thin, which keeps values firm. Expect a club membership structure on top of your HOA. Ask for the current initiation and monthly dues in writing before you fall in love with a house, because that number is real and recurring.

Who it fits: Buyers who want a private, full-service country club lifestyle and plan to use the golf and dining enough to justify the membership. If you are not going to touch the course, you are paying for amenities you won’t use.

PGA Village and Sabal Creek

PGA Village is a big, established golf community, and Sabal Creek is the gated, lower-density enclave inside it that consistently commands the highest prices. You get custom estate homes on oversized lots, mature landscaping, and access to PGA Village’s courses, the Island Club, tennis, and a full activity calendar.

What it actually costs: Sabal Creek homes sit near the top of the Port St. Lucie market alongside Tesoro. PGA Village has CDD assessments to be aware of, and club access comes with its own membership costs. The combination of exclusivity and big lots is what holds the value here.

Who it fits: Golf-serious buyers who want a recognized name and a deep amenity package, and who like the idea of a quiet pocket inside a larger, lively community.

Tradition (the upscale enclaves)

Tradition is the master-planned, small-town-style community built around a walkable town square, with year-round events, shops, restaurants, and the Cleveland Clinic Tradition hospital right there. Most of Tradition is mid-market, but the higher-end neighborhoods inside it sell at a real premium, and demand for them stays strong because of the lifestyle and the healthcare access.

What it actually costs: Tradition is a CDD community, full stop. The convenience and the amenities are funded, and that funding is on your tax bill. The luxury enclaves price above the Tradition average but generally below Tesoro and Sabal Creek. For a lot of buyers, Tradition is the sweet spot of “nice and easy” without the country club commitment.

Who it fits: Buyers who want walkability, events, dining, and a hospital five minutes away more than they want a golf membership. Retirees and remote professionals love it for exactly that reason.

Astor Creek Golf and Country Club

Astor Creek is one of the newer luxury plays in Port St. Lucie, a contemporary take on the country club model with a new championship course, a modern clubhouse, racquet sports, and resort-style amenities. The homes are upscale single-family with open layouts, energy efficiency, and golf or preserve views.

What it actually costs: Because it’s newer, much of the inventory is new construction, which means builder pricing, builder timelines, and a club membership structure you’ll want spelled out. New does not automatically mean cheaper to own once the club dues are added in.

Who it fits: Buyers who want a fresh, modern country club community and like being early in something rather than buying into a 20-year-old club.

Rivella

Rivella is a gated, master-planned community sitting right on the St. Lucie River, which is its whole pitch. You get a clubhouse, fitness center, pool, tennis, and trails through natural preserve, plus actual river access for kayaking, paddleboarding, and boating. Homes are luxury single-family and custom estates built to take advantage of the water and the light.

What it actually costs: Riverfront and new construction both carry a premium here, so Rivella prices above a lot of inland Port St. Lucie. Check for CDD and confirm what the HOA covers, especially anything tied to the waterfront amenities.

Who it fits: Water people. If your version of luxury is launching a kayak behind your house, this is your short list.

Vikings Lookout

Vikings Lookout is the boutique option, a small, established, low-density community known for large homes on spacious lots with lake or canal views. It’s quiet, private, and light on the big shared amenities, which is the point. You’re buying privacy and lot size, not a clubhouse.

What it actually costs: Limited inventory keeps prices firm. Lower amenity overhead can mean lower dues than the big golf communities, so this is worth a look if you want a high-end home without a country club bill attached.

Who it fits: Buyers who want space, water views, and quiet, and who would rather not pay for amenities they won’t use.

The riverfront pockets nobody puts on the list

Beyond the named communities, some of the most expensive homes in Port St. Lucie are simply the older, established homes along the St. Lucie River and its navigable canals, where deep-water access and a private dock can push a property’s value well past its neighbors. These do not always show up in “community” roundups because they are not master-planned developments, but if waterfront and boating are your priority, your agent should be pulling these too.

The CDD bond thing the other guides skip

I’m going to say this twice because it matters. Many of Port St. Lucie’s master-planned communities, including big names you’ll see on every list, carry a CDD assessment. It funds the community’s original infrastructure and it sits on your annual tax bill on top of regular property taxes.

It’s not a reason to avoid these communities. It’s a reason to ask the question before you write an offer. Get the CDD amount, find out how many years are left on the bond, and ask whether it can be paid off. I have watched buyers fall for a house and then get surprised by a monthly number that was hundreds higher than they planned. Two minutes of homework prevents that.

While you’re at it, ask about insurance. Newer construction with impact windows and current building codes often insures better than older waterfront, and on the Treasure Coast that line item moves the math more than people expect.

How Port St. Lucie luxury compares to Vero Beach

Here’s the honest part. If you’re shopping the top of the Port St. Lucie market, you owe yourself a 30-minute drive north before you sign anything.

Vero Beach and Indian River County have a different luxury ceiling. Private island communities like John’s Island, Windsor, and Orchid Island, plus mainland clubs like Grand Harbor and Indian River Club, offer a level of exclusivity and oceanfront access that Port St. Lucie does not really have an equivalent for. You can see how those stack up in my guide to Vero Beach country clubs and golf communities [confirm URL]. The trade-off is that the very top of the Vero island market runs higher than Port St. Lucie, so it’s a real comparison, not an automatic upgrade.

What surprises buyers is the middle. Plenty of buyers assume Port St. Lucie is cheaper across the board, but once you add CDD bonds and mandatory club dues into a Port St. Lucie golf community, a comparable Vero Beach home can land in the same monthly range with more privacy and a shorter beach drive. It depends entirely on the specific homes, which is the whole reason to compare them side by side. I broke the two markets down in detail in Vero Beach vs. Port St. Lucie [confirm URL], and if you’d rather skip the country club premium entirely, my post on no-HOA neighborhoods on the Treasure Coast [confirm URL] covers the other end of the spectrum.

If a move to the area is the bigger picture for you, start with my complete guide to moving to Vero Beach. It walks through neighborhoods, costs, and the practical stuff most listing sites leave out.

Which one is right for you?

A quick way to narrow it down:

  • Want the most prestigious address and you’ll use the golf? Tesoro Club or Sabal Creek in PGA Village.
  • Want walkability, dining, events, and a hospital nearby without a golf commitment? Tradition’s upscale enclaves.
  • Want new and modern in a fresh country club? Astor Creek.
  • Want to live on the water? Rivella, or an established riverfront home with a dock.
  • Want a big home, big lot, low amenity overhead, and quiet? Vikings Lookout.
  • Not sure Port St. Lucie is even the right town? Compare it against Vero Beach first.

Let’s find the right one for your number, not just the prettiest listing

I work the entire Treasure Coast, so I can pull Port St. Lucie and Vero Beach options side by side and show you the real monthly cost of each, CDD and dues included, before you get attached to anything. If you tell me your budget, your lifestyle, and your timeline, I’ll send you a short list that actually fits.

Reach out through my contact page and let’s talk through it.

Rent to Own Homes In Vero Beach

Rent to Own Homes in Vero Beach: What’s Real and What’s a Lead Trap

  • True rent to own homes in Vero Beach are rare. The big listing sites showing hundreds of them are mostly displaying regular listings behind a registration wall that signs you up for marketing calls.
  • A real rent to own deal is a lease with an option to buy, and the terms (option fee, rent credits, purchase price, deadline) all favor whoever writes the contract, which is usually the seller.
  • The national sites are working with stale data. Some still describe Vero Beach homes at $150,000 to $200,000. The actual median sale price here is around $400,000 as of 2026.
  • If your credit or down payment is the obstacle, you usually have better paths than rent to own: FHA loans, down payment assistance, or negotiating seller concessions in today’s buyer-friendly market.
  • Before you sign any lease option agreement, have a local agent and a real estate attorney review it. The downside of a bad one is losing every dollar you put in.

If you searched “rent to own homes in Vero Beach,” you probably landed on one of those national sites promising hundreds of listings, no credit check required, just enter your name, email, and phone number to see the details.

I’m a licensed Florida real estate agent here in Vero Beach, and I want to save you some frustration: most of what those sites show you isn’t rent to own at all.

What those “rent to own” listing sites actually are

Pull up the big aggregators for Vero Beach and look closely. You’ll notice a few things.

First, many of the properties aren’t in Vero Beach. Scroll through and you’ll find homes in Port St. Lucie, Palm Bay, Fort Pierce, and Melbourne, some of them 45 minutes to an hour away, labeled as Vero Beach results.

Second, most listings are tagged something like “Rent to Own Eligible.” That’s not a rent to own deal. That’s usually a regular for-sale or rental listing the site has scraped and repackaged. There’s no seller on the other end who has agreed to lease-option terms.

Third, the fine print on the registration form typically says that by clicking continue, you agree to be contacted by the site and third parties, including by pre-recorded messages and autodialers. You’re not unlocking listings. You’re becoming the product.

And fourth, the local “market info” on these pages is often years out of date. I’ve seen these sites tell buyers that Vero Beach homes sell for $150,000 to $208,000. The real median sale price here is around $400,000 right now. If a site is off by that much on the most basic fact about our market, don’t trust it on anything else.

How a real rent to own deal works

Legitimate rent to own arrangements do exist. They’re just rare, private, and almost never sitting in a searchable database. Here’s the actual structure:

The lease option. You sign a lease, usually 1 to 3 years, plus an option agreement that gives you the right (not the obligation) to buy the home at a set price before the lease ends. You pay an upfront option fee, typically 1 to 5 percent of the purchase price, which is usually non-refundable.

The lease purchase. Same setup, except you’re obligated to buy at the end. This is the riskier version for you, because if your financing falls through, you’re in breach of contract.

Rent credits. Some agreements apply a portion of your monthly rent toward the eventual purchase. Sounds great, but the rent is usually set above market to fund those credits, and if you don’t close, the credits vanish along with your option fee.

The core problem: the person who benefits most from a rent to own contract is the person who wrote it. If you miss a payment, miss the purchase deadline, or can’t qualify for a mortgage when the option expires, you typically forfeit everything and walk away as a tenant who overpaid.

Why rent to own inventory is so thin in Vero Beach

Sellers here don’t need to offer creative financing to move a house. Even in a slower market, Vero Beach attracts a steady stream of relocating buyers from the Northeast and Midwest, plus retirees and cash buyers who close quickly with no financing contingency. A seller weighing a clean cash offer against a three-year lease option with a maybe-buyer picks the cash almost every time.

The rent to own deals that do happen locally tend to come from three places: individual owners who’ve struggled to sell an unusual property, investors running lease-option programs as a business model, and occasionally family or word-of-mouth arrangements. None of those show up on a national aggregator.

Better paths if credit or cash is the obstacle

Most people searching for rent to own homes in Vero Beach aren’t in love with the rent to own structure. They want to own a home and believe their credit score or down payment locks them out of a mortgage. Often that belief is wrong, or at least more fixable than they think.

FHA loans. You can qualify with a credit score in the 580s and a down payment as low as 3.5 percent. On a $300,000 home on the mainland, that’s $10,500 down, which is often less than the option fee plus rent premium you’d sink into a lease option.

Down payment assistance. Florida runs programs that help eligible buyers with down payment and closing costs, including options aimed at first-time buyers and workers in certain professions. Whether you qualify depends on income, the property, and current program funding, which changes, so this is a conversation to have with a local lender before you assume you’re out.

Negotiating in today’s market. Right now Vero Beach is a buyer-friendly market. Inventory is up, most listings are taking price cuts, and homes are selling below asking on average. That means seller-paid closing costs and rate buydowns are on the table in ways they weren’t two years ago. A motivated seller covering $10,000 of your closing costs solves the same cash problem a rent to own deal pretends to solve, without the forfeiture risk.

A 12-month plan. If your credit genuinely isn’t mortgage-ready, renting normally for a year while you fix it usually beats a lease option. You keep your flexibility, you don’t pay above-market rent, and you’re not racing a contract deadline. I’ve watched buyers go from “no lender will touch me” to closed in under 18 months with a decent credit repair plan.

If you’re moving here from out of state, my complete guide to relocating to Vero Beach covers the cost side in detail, and I’ve written a specific breakdown for buyers coming from New York.

If you still want to pursue rent to own

Sometimes it’s genuinely the right fit, usually for self-employed buyers with strong income but a short earnings history. If that’s you, protect yourself:

  • Get the purchase price locked in writing now, not “market value at time of purchase.”
  • Record the option or a memorandum of it with Indian River County so the seller can’t sell out from under you.
  • Verify the seller actually owns the home and isn’t behind on the mortgage. If they get foreclosed on, your option can get wiped out.
  • Have a Florida real estate attorney review the contract before you sign. The few hundred dollars is the cheapest insurance in this whole process.
  • Confirm who pays taxes, insurance, and repairs during the lease. In many lease options, that’s you, even though you don’t own anything yet.

I can also keep an eye out for legitimate lease-option opportunities and seller-financing situations as they come up. They’re not common, but they exist, and they never make it to the national sites.

Talk to someone local before you hand over your phone number

The gap between what the rent to own sites promise and what actually exists in this market is wide. Before you register on one of those platforms, spend 15 minutes talking to someone who works these streets every day. I’ll give you an honest read on whether rent to own, a low-down-payment loan, or a normal purchase with seller concessions gets you into a home fastest.

Call or text me at (772) 999-4457, send me a message here, or start with my Vero Beach communities guide to see which neighborhoods fit your budget. There’s no charge to talk, and I won’t sell your number to an autodialer.

Related reading:

What Is Considered A Mansion?

Overview of what is considered a mansion

  • There is no legal definition of a mansion. Most agents work from a square footage floor of around 5,000 square feet, though plenty now reserve the word for homes north of 7,000 to 8,000.
  • Size alone does not make a mansion. It needs the luxury finishes, the amenities, and usually the land to back it up.
  • A McMansion is a big house that skips the quality and the lot, so it reads as size without substance.
  • The term is relative to location. A 4,000 square foot home reads very differently in Manhattan than it does on the Vero Beach barrier island.
  • In Vero Beach, the homes that actually earn the label sit on the island in places like John’s Island, Orchid Island, and Windsor.

Buyers ask me this more often than you would think. Someone tours a 6,000 square foot home with a pool and a guest house and wants to know if they just bought a mansion, or if the word is reserved for something grander. The honest answer is that nobody owns the definition. There is no building code, no tax form, and no MLS checkbox that turns a big house into a mansion. That does not make the word meaningless, though. After selling real estate on three continents, I can tell you there is a rough consensus most agents work from, and it is worth understanding whether you are buying, selling, or just curious about that big house down the street.

The square footage everyone argues about

If you want a number, here is the one most people land on. Historically, 5,000 square feet was the line. A home that size was roughly double the average American house, so it stood out as something special.

The problem is that houses keep getting bigger. The typical American home runs around 2,000 square feet, and even new construction usually lands under 2,800. As the baseline crept up, so did the bar for what feels truly large. That is why a lot of agents now use 7,000 to 8,000 square feet as the real threshold, and in some high-end markets the number climbs well past that.

So the practical answer is a range. Somewhere between 5,000 and 8,000 square feet is where most people start calling a home a mansion, with the exact line depending heavily on where the house sits. For perspective, the White House is about 55,000 square feet, and it does not even crack the list of the largest private residences in the country.

Size is the entry fee, not the whole ticket

Square footage gets you in the conversation. It does not finish it. A 6,000 square foot home built with builder-grade everything is just a big house. A mansion carries a level of quality and design that a large floor plan alone cannot fake.

When I walk a buyer through a home that genuinely qualifies, the size is almost the least interesting part. What sets it apart is the rest of the package:

  • High-end materials and finishes. Think stone and real wood over laminate, custom millwork, imported tile, and fixtures that were specified rather than picked off a shelf.
  • Purpose-built rooms. A true mansion has spaces designed for specific uses. A home theater, a wine room, a gym, a real library, a catering kitchen behind the main kitchen.
  • Amenities that go beyond the house. Pools, summer kitchens, guest houses, and on larger estates, things like tennis courts or boat docks.
  • Land. A mansion almost always sits on a lot that gives it room to breathe. A huge house crammed onto a small parcel does not read the same way.

A home can be enormous and still feel light on all of this. That is the difference between a big house and a mansion.

Mansion vs. McMansion

This is the distinction that trips people up, and it matters if you are spending real money.

A McMansion has the square footage of a mansion without the substance. These homes are usually built out of proportion to their lots, pushing right up to the property line, and they lean on showy entryways and oversized garages instead of genuine craftsmanship. The materials tend to be cheaper, the architecture tends to be generic, and the whole thing often ages faster than a well-built home half its size.

You can love a McMansion for the space and the price. Just go in with your eyes open about what you are buying. When I represent a buyer at this size, a big part of the job is pointing out where the money actually went, because the listing photos will never tell you that on their own. If you want a sense of how to read pricing on a larger home before you make an offer, my reasonable offer chart walks through how to think about it.

Why the number depends entirely on where you are

Location does more to define a mansion than any single square footage figure.

In New York City, a 2,000 square foot townhouse or penthouse can absolutely carry the label, because space there is scarce and expensive. In parts of California, agents would not call anything under 20,000 square feet a mansion, and the word itself has fallen out of fashion in a lot of luxury circles. Out in ranch country, a mansion might come with hundreds of acres attached.

The useful rule of thumb is relativity. A home is often treated as a mansion when it is three to four times the size of the typical house around it, even if that number would look ordinary somewhere else. So the same 5,000 square foot home can be a clear mansion in one zip code and just a nice big house in another.

What counts as a mansion in Vero Beach

Here on the Treasure Coast, the mansions cluster where you would expect, which is the barrier island. The strip between the Indian River Lagoon and the Atlantic is where Vero’s trophy addresses live, and where prices climb fast.

If you are shopping at this level, you are looking at communities like John’s Island, Orchid Island, Windsor, The Moorings, and Riomar. These are gated and club communities where the homes have the size, the finishes, and the oceanfront or golf-frontage land that the word implies. I break all of them down in my guide to Vero Beach communities, sorted by lifestyle rather than by prestige ranking.

Cross the bridge to the mainland and the math changes. Gated golf communities like Grand Harbor deliver large, well-built homes with resort amenities, often at a meaningful discount to the island. Whether you call one of those a mansion depends on the home, but the value proposition is strong, which is exactly why so many relocating buyers land there. And it does not hurt that Florida has no state income tax, which changes the calculus for anyone moving down from the north. If that is you, start with my complete Vero Beach relocation guide.

Should you call your home a mansion when you sell it?

Probably not, and this surprises sellers every time.

Most agents avoid the word in listings, for two reasons. First, since there is no firm definition, the term promises something it cannot reliably deliver, and a buyer who shows up expecting a mansion and finds a large house is a disappointed buyer. Second, at this price point, the word can come across as trying too hard. Buyers shopping for an eight figure island estate are not looking for the listing that shouts “mansion” in the headline.

The exception is a home with genuine history, where the word is part of the property’s actual identity. Outside of that, you are usually better off letting the photos, the square footage, and the features do the talking. That is the approach I take with every high-end listing, and it works.

Thinking about buying or selling a larger home in Vero Beach?

Whether you are trying to figure out if a property is truly a mansion or just a big house, or you want to know what your own home should really be called when you list it, that is the kind of thing I sort out for clients all the time. Tell me your budget, your must-haves, and whether you are full time or seasonal, and I will send you what actually fits. Get in touch here or call (772) 999-4457.

Related reading

Vero Beach Home Insurance Cost: What Homeowners Pay In 2026

Overview

  • Florida home insurance stabilized in 2026 after years of brutal increases, with the statewide average now around $3,815 a year and Citizens, the state insurer of last resort, cutting rates an average of 8.7%, its first decrease since 2015.
  • A typical single-family Vero Beach home insurance cost runs roughly $3,000 to $5,000 a year to insure, with barrier island and oceanfront homes costing more and newer inland homes with a good roof costing less.
  • Wind and flood are separate policies in Florida, your homeowners policy does not cover flood, and your hurricane deductible is a percentage of your home’s value rather than a flat dollar figure, so keep that cash on hand.
  • If you’re a snowbird buying a winter place, seasonal occupancy changes how carriers underwrite you, and homestead-only perks like the My Safe Florida Home grant won’t apply, though wind mitigation discounts still will.
  • The biggest single lever on your premium is the house itself, because a newer roof, impact windows, and a hip roof shape can cut thousands off the bill, so shop the hardened house.

If you’re calling me from New Jersey, Ohio, or Connecticut about buying in Vero Beach, the first question is almost never about the house. It’s “what’s the insurance going to cost me, and can I even get it?”

I get it. For about three years, Florida home insurance was a horror story in every national headline. Carriers went insolvent, rates doubled, and people you know swore the state was becoming uninsurable. That story was real. It’s also two years out of date.

Here’s where things actually stand in 2026, what a Vero Beach home really costs to insure, and the handful of things Northern buyers consistently get wrong before they close.

The scary headline you remember is from 2023

Florida’s homeowners market spiked hard from 2020 to 2024. The statewide average climbed from about $2,520 to $4,480 in three years, a 78% jump. Then it turned.

A few things changed at once. The legislature passed reforms in 2022 and 2023 that eliminated one-way attorney fee awards and restricted the assignment-of-benefits abuse that was driving a flood of insurance litigation. Insurance lawsuits have fallen more than 35% since 2021. Seventeen new insurance companies have entered the Florida market since those reforms. Reinsurance costs, the price insurers pay to insure themselves, eased after a couple of milder storm seasons.

The result is the thing nobody expected: Vero Beach home insurance cost coming down. The statewide average annual premium including wind coverage is now about $3,815, up only around 6% from a year earlier, a fraction of the double-digit increases from before. Citizens filed for an average 8.7% rate decrease for 2026, its first decrease since 2015, with South Florida counties seeing cuts as large as 14%. Citizens has also shrunk from about 1.42 million policies in late 2023 to roughly 395,000 by January 2026 as private carriers absorbed those homes. That shrinkage is the clearest sign the private market is healthy again.

None of this means cheap. Florida is still the most expensive state in the country for home insurance. But “expensive and stable” is a very different planet from “spiking and uninsurable,” and it changes the math on buying here.

What Vero Beach home insurance actually costs in 2026

Now the number you came for.

For a typical single-family home in the Vero Beach area, plan on roughly $3,000 to $5,000 a year. Florida Office of Insurance Regulation data puts the average single-family property insurance cost in Indian River County around $3,386, and independent agents writing here generally quote $3,000 to $4,800 a year for about $300,000 in dwelling coverage.

That’s a wide range, and the reason for the spread matters more than the average. Four things move your Vero Beach premium more than anything else:

  • Distance from the water. This is the big one. A home on the barrier island in 32963, anywhere near the ocean, lives in a completely different pricing world than a home a few miles inland in 32966 or 32968. Indian River County sits in a high wind zone rated for 140 to 160 mph, and windstorm reinsurance is the single largest piece of your premium.
  • Roof age and type. Carriers care about your roof more than your kitchen. A roof under about 15 years old, ideally a hip shape (sloped on all four sides) rather than a gable, can be the difference between an easy quote and a flat decline.
  • Dwelling value. You’re insuring the cost to rebuild, not the purchase price and not the land. A $1.5M oceanfront rebuild costs far more to cover than a $350,000 mainland home, even before the coastal surcharge.
  • Your deductible structure. More on this in a second, because the hurricane deductible is where Northern buyers get the biggest surprise.

If it helps, I can pull a rough insurance estimate on any specific Vero Beach listing before you ever make an offer. It’s a five-minute conversation that saves people a lot of grief.

Wind, flood, and the deductible math nobody explains up north

This is the section I wish every out-of-state buyer read first, because it’s where the real misunderstandings live.

Your homeowners policy does not cover flood. Ever. In Florida, wind damage and flood damage are two separate policies. Your standard HO-3 homeowners policy covers wind, including hurricane wind. Flood, meaning rising water and storm surge, is a completely separate policy, usually through the National Flood Insurance Program (NFIP) or a private flood carrier. Most people assume “hurricane coverage” is one product. It isn’t.

Flood insurance in Florida averages somewhere between roughly $900 and $1,400 a year depending on the source and your specific property, and it’s driven almost entirely by your elevation and flood zone. Good news for Vero Beach specifically: the City participates in FEMA’s Community Rating System at a Class 7 level, which gives most NFIP policyholders a 15% discount inside high-risk flood zones and 5% outside them. That’s a real, automatic savings most buyers never think to ask about.

Whether you’re required to carry flood depends on your zone and your lender. If the home is in a high-risk zone (anything starting with A or V on the FEMA map) and you have a mortgage, flood is mandatory. And if you end up with a Citizens wind policy, know this: starting in 2026, Citizens requires flood coverage for any home insured at $400,000 or more in dwelling value, regardless of flood zone.

Now the deductible, and this is the one that catches people. Your hurricane deductible is a percentage, not a flat dollar amount. A normal claim like a kitchen fire or a burst pipe might carry a $2,500 deductible. But for hurricane damage, Florida policies use a separate deductible that’s typically 2%, 5%, or even 10% of your dwelling coverage. On a $400,000 home, a 2% hurricane deductible means $8,000 out of your own pocket before the insurer pays a cent. That’s not a reason to panic. It’s a reason to keep that cash available and to know your number before a storm shows up, not after.

The snowbird wrinkle: insuring a home you won’t live in year round

If you’re buying a winter place and keeping your primary home up north, a few things change, and your insurance agent back home won’t warn you about any of them.

Seasonal occupancy affects your coverage.

Carriers underwrite a home differently when it sits empty for months, especially during hurricane season. Many write it as a secondary or seasonal residence, sometimes with conditions about how often it’s checked on or whether the water is shut off while you’re away. Be upfront about how you’ll use the place. A policy written for an owner-occupied primary home can fall apart at claim time if the carrier later learns it was actually vacant half the year.

Homestead-only perks don’t apply.

This is the one that stings. Florida’s My Safe Florida Home program offers a free wind mitigation inspection and a matching grant of up to $10,000 for hurricane-hardening upgrades like impact windows and roof reinforcement. But the grant is limited to owner-occupied primary residences with a homestead exemption. A seasonal second home doesn’t qualify for the grant dollars. Same story with the homestead property tax exemption and the Save Our Homes assessment cap, which lower your tax bill but not your insurance, and only on a primary residence.

Here’s the part that still works in your favor: even without the grant, you can pay for a wind mitigation inspection yourself, and any qualifying features it documents translate into Vero Beach home insurance cost discounts that Florida insurers are required to apply. So hardening the house still pays off. You just fund it yourself instead of splitting the cost with the state.

How to lower your Vero Beach home insurance cost

The levers, in rough order of impact:

  • Buy the hardened house. This is the highest-leverage decision you’ll make, and it happens before you own anything. Between two similar Vero Beach homes, the one with a newer roof, impact-rated windows and doors, and a hip roof can cost thousands less per year to insure. Factor insurance into which house you choose, not just the list price.
  • Get a wind mitigation inspection. It runs around $75 to $150 and documents every storm-resistant feature your home already has. Hand it to your carrier. The discounts can be substantial, and they’re not optional for the insurer to honor.
  • Use My Safe Florida Home if you’ll homestead. If Vero is becoming your primary residence and the home was permitted before January 1, 2008, the program’s match is close to free money for hardening. The state pays $2 for every $1 you spend, up to a $10,000 grant. Funding moves through a priority queue, so apply early when your window opens.
  • Shop with an independent agent. An independent agent quotes multiple carriers against your specific address instead of selling you one company’s product. With seventeen new carriers in the market, the gap between the best and worst quote on the same house is wider than it’s been in years.
  • Raise your deductible, carefully. Moving from a 2% to a 5% hurricane deductible lowers your premium, but only do it if you can comfortably cover that larger number in cash. It’s a genuine tradeoff, not a free win.
  • Order a four-point inspection on older homes. If the home is over about 30 years old, most carriers want a four-point inspection (roof, electrical, plumbing, HVAC) before they’ll write it. Knowing the results early keeps a deal from blowing up at the last minute.

The buyer’s move: get the quote before you’re committed

The mistake I watch Northern buyers make over and over is treating insurance as a closing-table formality. They fall in love with a house, go under contract, and only learn the real insurance number when the lender orders it weeks later. Sometimes that number changes whether the house even makes sense.

Do it backwards. Get a real insurance quote during your inspection period, while you can still walk away or renegotiate. On an older or coastal home, line up the wind mitigation and four-point inspections early. Confirm the flood zone and pull a flood quote too. And budget your hurricane deductible as cash you keep on hand, the same way you’d keep an emergency fund.

Florida home insurance in 2026 is expensive, stable, and very manageable once you understand the moving parts. The buyers who get burned are the ones who guess. The ones who do fine are the ones who run the numbers on the specific house before they’re emotionally and contractually locked in.

That’s exactly the part I help with. If you’re thinking about buying in Vero Beach and you want to know what a specific home will really cost to own, insurance included, reach out and let’s run the numbers together before you make a move.

Related reading